Economy
29 March 2023
Ecommerce expected to grow 10-12% in 2023: NRF
The National Retail Federation is expecting overall retail growth of 4-6%.
(Courtesy of National Retail Federation)

The National Retail Federation is expecting overall retail growth of 4-6%.
(Courtesy of National Retail Federation)
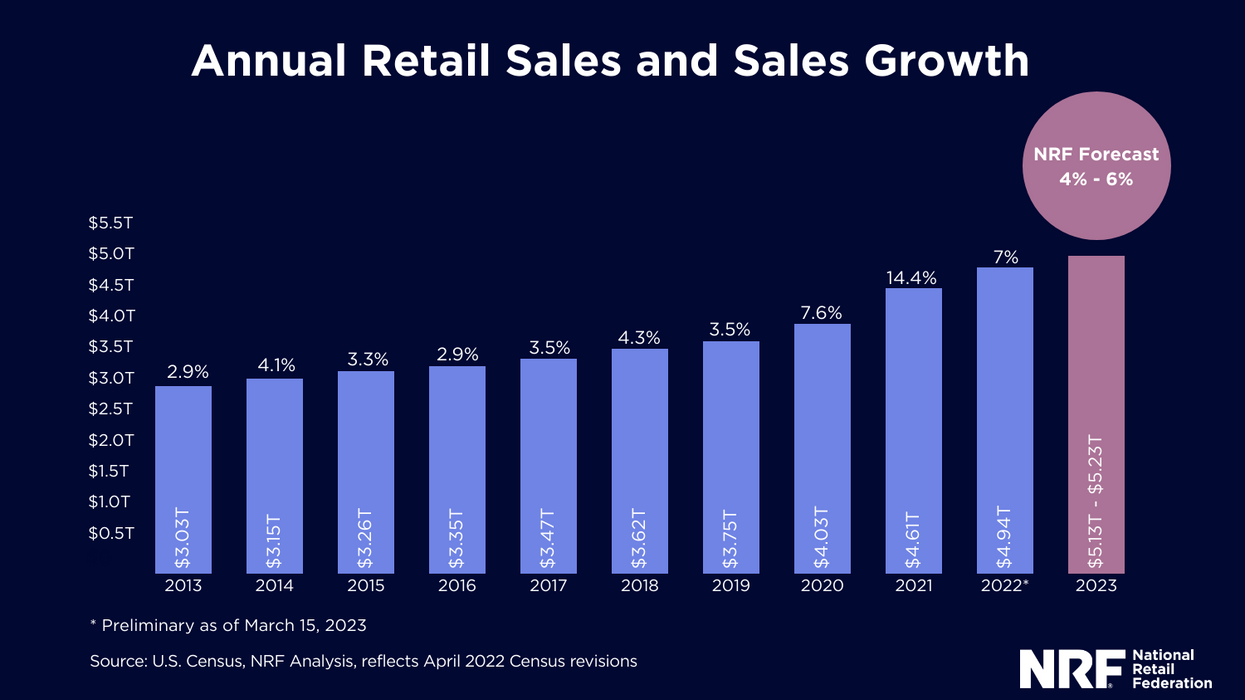
U.S. retail sales are expected to increase between 4 and 6% in 2023 over 2022, according to a new forecast from the National Retail Federation.
That would see retailers bring in revenue in the range of $5.13 trillion and $5.23 trillion for the year.
The estimate, which excludes restaurant, gas and motor vehicle sales, is above pre-pandemic average retail growth of 3.6%. However, it is below the pandemic years. In 2022, growth topped 7%.
Ecommerce and non-store sales are expected to outpace overall retail, with growth between 10 and 12% from 2022. That would range in revenue from $1.41 trillion to $1.43 trillion. While the inclusion of non-store sales from catalogs and vending machines mean this category isn't only ecommerce, the forecast would come well above the 7% growth of ecommerce in 2022, as observed by the federal government. Insider Intelligence released a separate projection on Wednesday that forecast 10% growth.
NRF said much of the ecommerce growth is now driven by multichannel sales that cross both digital and physical shopping. Physical stores continue to account for 70% of total retail, NRF notes.
The forecast arrives at a time of continued uncertainty surrounding the economy. While the supply chain issues and swings in demand of the pandemic have mostly moderated, high inflation and interest rates that are working to bring it down are combining to create headwinds on the consumer. Factor in the Silicon Valley Bank collapse’s ripple effects, and it remains a difficult job to predict results.
“While it is still too early to know the full effects of the banking industry turmoil, consumer spending is looking quite good for the first quarter of 2023,” said NRF Chief Economist Jack Kleinhenz, in a statement. “While we expect consumers to maintain spending, a softer and likely uneven pace is projected for the balance of the year.”
Here’s a look at key economic drivers of the forecast, as presented by Kleinhenz:
GDP: Overall U.S. economic activity is projected to rise between 0 and 1% in 2023. That’s below the 2.1% growth of 2022. Consumer spending makes up 70% of GDP, so this is a significant indicator for retailers.
Labor market: Jobs are a prime indicator of demand, and continued strength in new jobs created and wage growth to start the year is putting the year off to a fairly healthy start, despite inflation. But many economists believe the impact of interest rate hikes will eventually slow down job growth, and give way to a rise in unemployment above 4%, which would be up from its current historic lows later in the year.
Inflation: High prices have weighed on consumers over the last year. While it has come down to begin 2023, the pace of the decline is proving to make inflation stubborn. In the coming months, Kleinhenz said inflation is expected to cut in half to a range of 3-3.5%
Savings: Consumers continue to have access to healthy savings following the pandemic, but that could begin to wane more significantly as the year goes on, especially as continued high inflation leaves shoppers paying more for essentials like food, gas and rent.
Banking: One question mark is how the banking crisis that stemmed from the collapse of Silicon Valley Bank will filter out to consumers. Kleinhenz said it remained too early to determine the direct impact on consumption, but economists at the Federal Reserve have said it could lead to tighter credit conditions that will affect households.Campbell Soup Company CEO Mark Clouse offered thoughts on messaging amid inflationary shifts in consumer behavior.
After months of elevated inflation and interest rate hikes that have the potential to cool demand, consumers are showing more signs of shifting behavior.
It’s showing up in retail sales data, but there’s also evidence in the observations of the brands responsible for grocery store staples.
The latest example came this week from Campbell Soup Company. CEO Mark Clouse told analysts that the consumer continues to be “resilient” despite continued price increases on food, but found that “consumers are beginning to feel that pressure” as time goes on.
This shows up in the categories they are buying. Overall, Clouse said Campbell sees a shift toward shelf-stable items, and away from more expensive prepared foods.
There is also change in when they make purchases. People are buying more at the beginning of the month. That’s because they are stretching paychecks as long as possible.
These shifts change how the company is communicating with consumers.
Clouse said the changes in behavior are an opportunity to “focus on value within our messaging without necessarily having to chase pricing all the way down.”
“No question that it's important that we protect affordability and that we make that relevant in the categories that we're in," Clouse said. "But I also think there's a lot of ways to frame value in different ways, right?”
A meal cooked with condensed soup may be cheaper than picking up a frozen item or ordering out. Consumers just need a reminder. Even within Campbell’s own portfolio, the company can elevate brands that have more value now, even if they may not always get the limelight.
The open question is whether the shift in behavior will begin to show up in the results of the companies that have raised prices. Campbell’s overall net sales grew 5% for the quarter ended April 30, while gross profit margins held steady around 30%. But the category-level results were more uneven. U.S. soup sales declined 11%, though the company said that was owed to comparisons with the quarter when supply chains reopened a year ago and expressed confidence that the category is seeing a longer-term resurgence as more people cook at home following the pandemic. Snacks, which includes Goldfish and Pepperidge Farm, were up 12% And while net sales increased overall, the amount of products people are buying is declining. Volumes were down 7%.
These are trends happening across the grocery store. Campbell is continuing to compete. It is leading with iconic brands, and a host of different ways to consume them. It is following that up with innovation that makes the products stand out. Then, it is driving home messaging that shows consumers how to fit the products into their lives, and even their tightening spending plans.
Campbell Soup is more than 150 years old, and has seen plenty of difficult economic environments. It is also a different business today, and will continue to evolve. At the end of the day, continued execution is what’s required.
“If it's good food, people are going to buy it, especially if it's a great value,” Clouse said.